According to the Hackett Group, 43% of organizations are now actively pursuing AI deployment in procurement, nearly double the year before. However, only 12% report large-scale implementation of AI automation or similar uses.
Most of that difference comes down to two things: whether the process being automated was working before software was added, and whether someone was responsible for the rollout from the beginning.
This guide covers what procure-to-pay automation is, how to implement it properly, and where the rollout most often breaks down.
Key Takeaways:
- Automation replaces steps, not judgment: Automating tasks removes repetitive manual work, not the decisions that still need to be made by a person.
- Automating a broken process scales the errors in it: Clean data and defined rules need to come before automation, not after.
- Ownership needs to be defined before rollout, not discovered during it: Procurement, finance, and AP each own a different piece of the automated workflow, and unclear ownership is where automation stalls.
- apexanalytix strengthens the data that automated matching and payment controls depend on: apexanalytix validates vendor records before they factor into an automated decision.
What Is Procure-to-Pay Automation?
Procure-to-pay automation applies software to the repetitive parts of the P2P cycle: routing a requisition for approval, matching an invoice to a purchase order, or verifying a bank account before a payment is sent.
What automation removes here is repetitive, rule-based work. However, it doesn’t remove judgment: an unusual invoice, a flagged exception, or a vendor dispute still need to be resolved by a person.
What Procure-to-Pay Automation Replaces
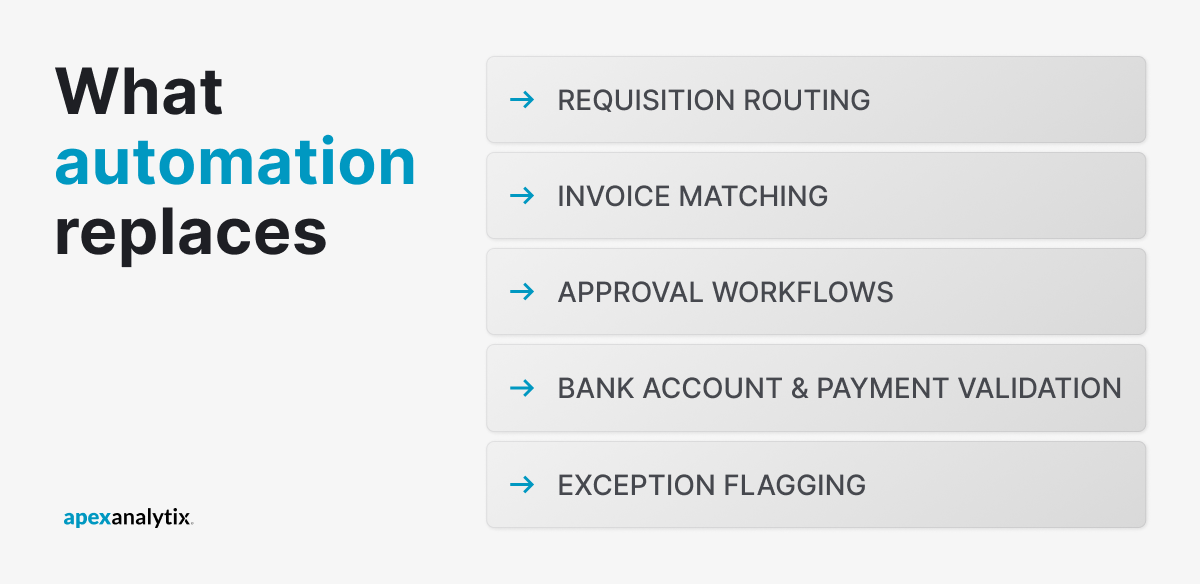
Automation doesn’t touch the whole P2P process at once. It targets specific manual steps, each with its own failure pattern when left to people and spreadsheets. Here are the manual steps that P2P automation replaces:
- Requisition routing: A request for goods or services used to move through email or paper, waiting on whoever happened to check their inbox that day. Automated routing sends it to the right approver based on category, amount, and department, without anyone having to remember who signs off on what.
- Invoice matching: Checking an invoice against its purchase order and receipt by hand is slow and prone to missing a near-duplicate. A vendor portal that captures structured invoice data at submission gives automated matching something consistent to check against, rather than a PDF someone has to key in first.
- Approval workflows: Manual approval chains stall when the approver is out or the request doesn’t fit a clear category. Automated workflows route based on predefined rules, so an invoice doesn’t wait on one person’s calendar.
- Bank account and payment validation: A bank account change request processed on trust, rather than verified against the account holder, paves the way for payment fraud to get through. Automated validation checks the account against authoritative records before a payment goes out, every time, not just when someone remembers to ask.
- Exception flagging: A manual process either sends every invoice to a person or catches nothing at all. Automated matching separates the invoices that clear cleanly from the ones that need a human decision, so review time goes toward the transactions that actually need it.
Benefits of Procure-to-Pay Automation
Here are a few benefits that procure-to-pay automation brings to finance teams:
- Real-time spend visibility: A manual process shows spend only after invoices are entered and reconciled. Automated requisition and approval data gives finance a live view of committed spend as it happens, not weeks later.
- Lower fraud exposure: A bank account change verified automatically against authoritative records, rather than accepted on trust, closes the exact window a fraudulent request depends on. That verification happens the same way every time, regardless of who submitted the change or how convincing it looked.
- A complete audit trail by default: Every automated approval, match, and exception gets logged with a timestamp, so answering “why was this paid” doesn’t depend on someone’s memory of an email thread from six months ago.
- Fewer errors compounding downstream: A near-duplicate invoice or a mismatched purchase order caught automatically at the matching stage never reaches payment, instead of surfacing months later in an audit after the money has already left.
These outcomes depend on the same thing the rest of this guide covers: automation applied to a process worth automating, not bolted onto one that was already broken.
How to Implement Procure-to-Pay Automation Properly
Enterprises take different paths to a working rollout. Here’s one way to implement it properly:
- Audit the current process first: A process running on workarounds and exceptions will automate those same workarounds and exceptions. Mapping what people do day-to-day shows where automation will genuinely help.
- Start with the step that causes the most friction: Automating an easy, low-friction step first feels productive but leaves the real bottlenecks untouched. A contract compliance audit or a look at exception rates usually points to where errors and delays actually pile up.
- Roll out one process at a time: Automating requisitions, invoicing, and payments all at once means more can go wrong at launch, making it harder to tell which change caused which problem.
- Give procurement, finance, and AP clear ownership up front: Automation touches all three, and a stalled workflow can remain unresolved for days if no one knows which team is responsible for fixing it.
- Plan for exceptions before launch, not after: A workflow with no path for an unusual invoice either stops cold or lets that invoice through unchecked. Deciding in advance who reviews exceptions and what triggers that review keeps automation from breaking the first time something doesn’t fit the rule.
Choosing Your Procure-to-Pay Automation Approach
The right automation approach depends less on company size and more on how much the existing approval process fits a standard pattern. The table below compares the three most common paths.
| Approach |
Best for |
Trade-off |
| Off-the-shelf P2P software |
A process with approval rules that already match a fairly standard workflow |
Fast to implement, but an approval rule that doesn’t fit the standard flow gets expensive to customize |
| ERP-native workflow |
An organization already committed to a single ERP across finance and procurement |
Keeps purchasing and payment data in one system, but workflow changes tend to move slowly |
| Custom-built workflow |
A process with approval rules specific enough that a standard tool would require heavy customization anyway |
Fits the exact process, but only works if that process is well understood before building around it |
None of these approaches is the default answer. A well-documented current-state audit, the first step in the implementation sequence above, is usually what makes the choice between them clearer.
Common Pitfalls in Procure-to-Pay Automation
Procure-to-pay automation rollouts can run into a few recurring problems. Each one starts small and grows if nothing catches it early.
Skipping receiving confirmation
Matching an invoice against its purchase order alone, with no confirmation that the goods or services actually arrived, turns the matching step into a guess. A three-way match—invoice against PO against a receiving record—is what actually confirms payment is warranted, not just that the paperwork lines up.
Treating the rollout as an accounts payable project
The highest-value automation tends to happen upstream, at requisition and approval, not at the invoice. A rollout that only automates invoice processing leaves the requisition backlog and inconsistent approval routing untouched, while these exact steps are most likely to cause the delays finance actually notices.
Over-building for edge cases before the common flow works
Spending implementation time perfecting how automation handles a rare exception, while the everyday transaction still routes inconsistently, means the majority of volume never benefits from the work. The common flow should run cleanly before edge-case handling gets built around it.
Best Practices for Procure-to-Pay Automation
A rollout that launches cleanly can still drift off course months later. A few habits keep it working long after launch day, including:
- Matching automation depth to transaction risk: A routine, low-value purchase order doesn’t require the same scrutiny as a large payment to a new vendor. Applying uniform rules everywhere either slows down low-risk transactions unnecessarily or lets high-risk ones through with too little review.
- Revisiting automated rules as vendor behavior changes: A rule built around how a vendor submitted invoices last year can miss a new pattern this year. Tracking exception rates against actual vendor activity shows when a rule needs updating, rather than routing more exceptions around it.
- Treating post-payment review as part of the system, not a backup plan: Automated pre-payment controls catch most errors, but not all of them. A structured AP recovery audit catches what got through, and feeds what it finds back into the rules that let it through in the first place.
- Documenting why an exception rule exists, not just what it does: A rule with no recorded reasoning gets removed or ignored the first time someone doesn’t understand it, often reopening the exact problem it was built to close.
- Separating who requests, approves, and releases payment: When one person can do all three, an error or a fraudulent request has nothing standing in its way. Keeping these roles distinct means at least one other person reviews a transaction before money actually moves.
How apexanalytix Supports Procure-to-Pay Automation
Procure-to-pay automation only works if it’s checking against a validated vendor record in the first place. Verify the wrong record, and the payment can still clear even if it goes to the entirely wrong account.
apexanalytix checks that record before it factors into any automated decision and keeps checking it afterward, rather than treating verification as something that only happens once at onboarding.
The platform covers:
- Structured intake through a vendor portal: Captures invoice and requisition data at the point of submission instead of a PDF someone has to key in by hand
- Risk-based approval routing: Sends higher-risk vendors and transactions for deeper review, while clean, low-risk ones move through faster
- Bank account ownership validation: Confirms a payment detail change against the account holder before a payment goes out, closing the exact opening a fraudulent request depends on
- Near-duplicate invoice detection: Catches a resubmitted invoice under a slightly different number through automated overpayment prevention, the kind of near-match a standard three-way match passes through unnoticed
- Continuous vendor risk monitoring: Updates a vendor’s status as conditions change, instead of relying on data collected once at onboarding
- Priority-scored exception flagging: Assigns each flagged transaction a score based on likelihood and impact, so review time goes to the exceptions that actually need it
- Early payment discount scoring: Predicts which vendors will accept an early payment offer and at what rate, turning automated payment timing into a working capital decision, not just a scheduling one
- AP recovery audit: Reviews the full volume of historical disbursements against supplier statements, not a sampled subset, to recover value that already left the organization
Results at scale
Here are some examples of successful procure-to-pay automation with apexanalytix:
- A nationwide restaurant operator managing nearly 2,000 locations, each free to onboard its own local vendors, now captures $200,000 in early payment discounts every month. Fraud and risk checks now run at vendor setup instead of after the fact, and vendor records that once required manual paperwork, phone calls, and online research get validated automatically.
- ChampionX, a global leader in oilfield technology, faced overlapping ERP systems after a corporate divestiture. After expanding its use of apexanalytix’s overpayment prevention, the company saved $1.5 million in duplicate payments by automating a check that manual review had been missing across its newly merged systems.
The restaurant chain closed the distance upstream, at onboarding. ChampionX closed it downstream, at payment. Together, they show automation working at both ends of the same process.
Where in your payment process is a manual check handling something a system could verify automatically?
Get started with apexanalytix to see how validated data, automated matching, and continuous monitoring work together across your procure-to-pay process.
FAQs
1. Should a small business automate its full procure-to-pay process, or start with one piece of it?
Starting with one piece works better in most cases. Requisition and approval routing tend to produce the fastest visible improvement, before invoice matching and payment automation are added on top.
2. Does procure-to-pay automation replace an ERP system?
No. Automation connects to an ERP already in place, feeding it validated data and structured workflows rather than replacing the system that holds financial records.
3. How much manual review should remain after automation is in place?
Enough to handle exceptions a rule wasn’t built to catch. The goal is to route routine transactions automatically, not to eliminate human review entirely.
4. What’s the biggest sign a P2P automation rollout needs adjustment?
When exception queues keep growing instead of shrinking over time. That usually points to a rule that no longer matches how vendors or transactions actually behave.