Enterprise resource planning (ERP) controls can catch many invoice and payment errors, but they don’t catch every overpayment. Duplicate supplier records, inconsistent invoice data, manual exceptions, and payments spread across multiple systems can all create gaps that standard controls miss.
The 2026 Global Overpayment Report analyzed $3.25 trillion in spend and more than 400 million invoices and found that duplicate payments accounted for 18% of lost profit, while payments tied to canceled invoices, contracts, or services accounted for another 14%.
ERP controls work best when the system has complete transaction data and up-to-date information about the supplier, invoice, and underlying purchase.
In this article, we cover the relationship between ERP and overpayments, including seven reasons why ERP controls miss payment errors, how accounts payable (AP) recovery audits differ from transaction controls, and how recovery findings can strengthen future payment controls.
Key Takeaways:
- ERP controls can work as configured and still miss overpayments: Detection depends on the transaction data, matching rules, and system scope available when a payment is processed.
- Some overpayments originate outside the ERP’s rules: Business events that never reach the system, supplier-side credits, and manually released exceptions can create losses even when configured controls work as intended.
- Historical payment review adds visibility that transaction controls don’t provide: AP recovery audits bring together past payment data, supplier information, and claim validation to identify which potential overpayments are still recoverable.
- Recovery findings can strengthen future payment controls: Recurring issues can reveal narrow duplicate-detection criteria, inconsistent supplier master validation, risky exception workflows, or incomplete information handoffs.
- apexanalytix combines recovery with overpayment prevention: apexanalytix pairs AP Recovery Audit with its Overpayment Prevention Module to recover historical losses and add real-time payment analysis before releasing new funds.
What ERP Payment Controls Are Designed to Catch
ERP payment controls compare invoices with existing transaction records and configured rules before payment.
Common ERP payment controls include:
- Duplicate invoice checks: Compare fields such as supplier ID, invoice number, amount, currency, company code, and invoice date to flag an invoice that may already exist.
- Two- and three-way matching: Compare the invoice with the purchase order and, for three-way matching, the goods receipt. Differences in price, quantity, or received goods can trigger an exception.
- Tolerance rules: Set acceptable limits for differences between invoice and purchase order values. Transactions outside those limits can trigger a warning or block further processing, depending on the configuration.
- Approval workflows: Route invoices or exceptions to designated approvers before payment processing continues.
- Supplier master controls: Check supplier records for duplicate, incomplete, or invalid data that could affect invoice processing.
7 Ways Overpayments Can Pass ERP Controls
ERP controls can perform as configured and still miss payment errors when key information falls outside the checks they apply.
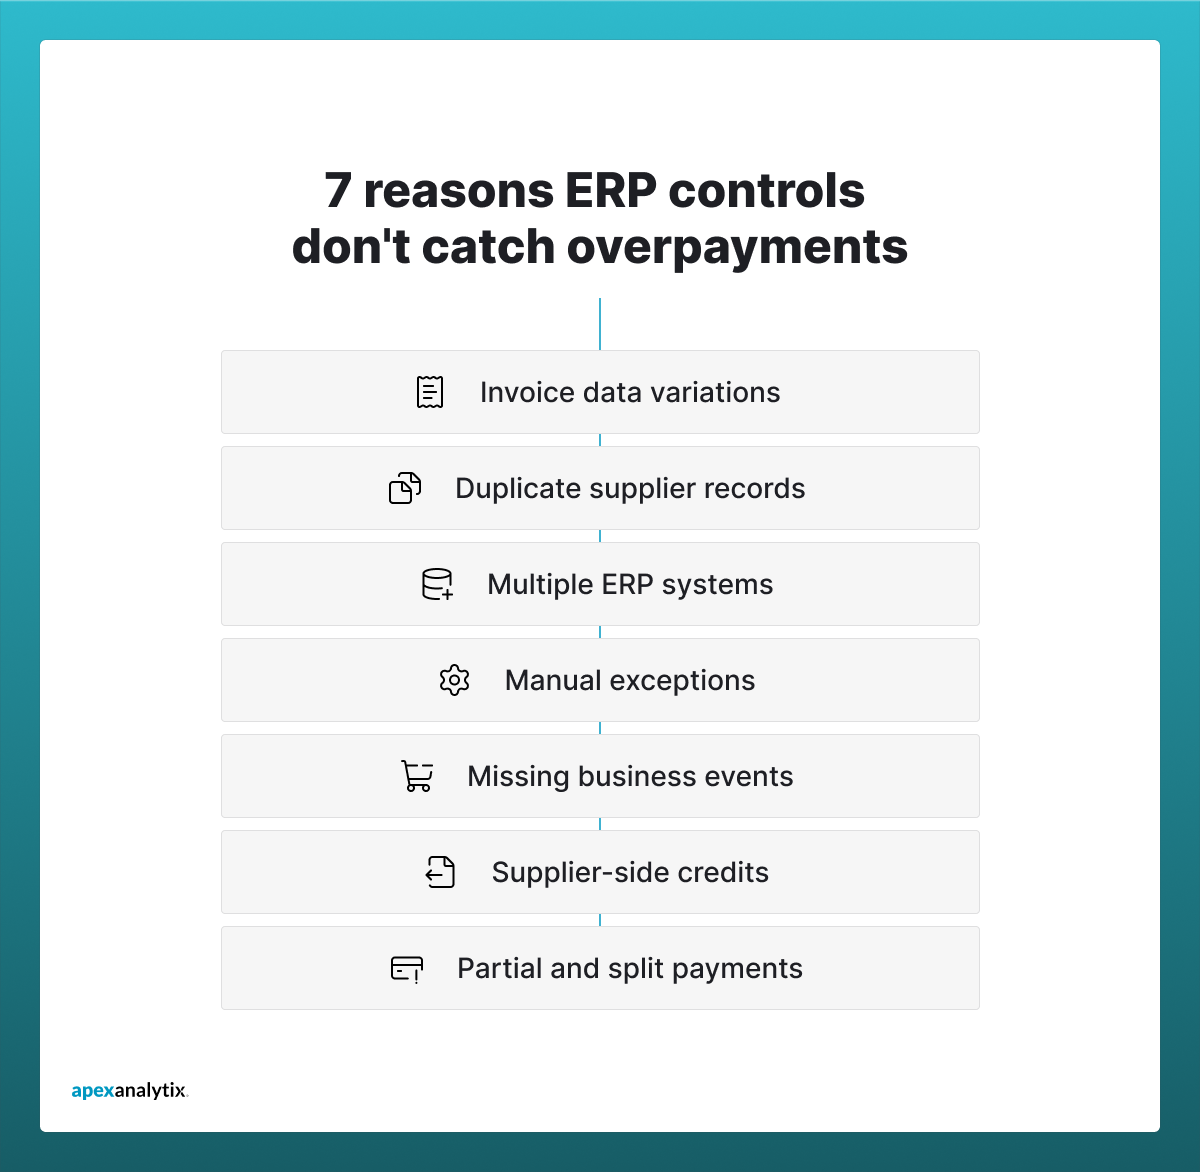
The seven reasons below explain how overpayments can still pass through established ERP payment controls:
1. Matching rules missing changes in invoice data
Duplicate checks depend on consistent invoice data. If the same invoice is entered with a changed reference or date, the second entry may not meet the conditions used to trigger a duplicate warning.
The same invoice can therefore appear different inside the ERP. For example:
| Original entry |
Second entry |
| INV-45821 |
INV45821 |
| July 15, 2026 |
July 16, 2026 |
If a duplicate check is configured to require an exact match on the reference or date, these differences can prevent the second entry from matching the original.
Some ERP platforms support broader or configurable duplicate checks, allowing more variations to be compared. Even then, enough matching data must be available for the second entry to connect to the original transaction.
2. Duplicate supplier records dividing payment history
A name change, acquisition, separate remittance address, or duplicate onboarding can create several records for one supplier, splitting its invoices and payments across separate transaction histories.
A duplicate check tied to one supplier ID may then evaluate an invoice without comparing it with payments recorded under another ID. The payment itself may be identical, while the supplier identity used for matching is different.
A structured third-party vendor management process can reduce this fragmentation by keeping supplier records connected across onboarding, active management, and offboarding.
3. Multiple ERP systems creating separate payment views
One enterprise may process supplier payments through several ERP environments.
NeuGroup’s 2026 TMS & ERP Benchmarking Report, based on more than 225 member companies, found that more than 20% of companies run multiple ERP systems.
Common causes include:
- Acquisitions: An acquired business continues using its previous ERP while systems are integrated.
- Regional operations: Countries or business units process invoices through separate ERP instances.
- ERP migrations: Old and new systems operate at the same time during the transition.
- Legacy systems: Older platforms remain active alongside newer ERP environments.
As a result, an invoice already paid in one environment can appear as new in another if the two payment histories aren’t compared.
4. Manual exceptions bypassing standard payment controls
Not every ERP warning stops payment. Depending on the system and its configuration, an employee may review and approve an exception.
Invoice exceptions are common. According to Ardent Partners, the average invoice exception rate sits at 18.4%.
The risk here comes from the exception path itself. A flagged invoice may be approved after review, while an urgent payment may follow a manual route with different controls from the standard payment process. In either case, the transaction can proceed with a different level of review.
5. ERP never receiving the event that changed what’s owed
Some overpayments begin outside AP rather than inside the payment system.
Canceled services, returned goods, reduced order quantities, or adjustments agreed elsewhere in the business can change what the company actually owes. If that change isn’t reflected in the ERP, the invoice can still match the records AP has.
For example, a company orders 100 units at $500 each. Before shipment, the order is reduced to 80 units, but the ERP still shows the original quantity. AP may approve $50,000 instead of the $40,000 actually owed, creating a $10,000 overpayment.
In this case, the overpayment stems from a business event that never reached the ERP, even though the invoice check worked as configured.
6. Supplier-side credits remaining outside internal records
Supplier-side credits create a different problem. The payment may already have been made, while the supplier’s records show a credit or balance that the buyer hasn’t recorded.
Unrecorded supplier amounts can include:
- Credits for returned goods
- Credits for canceled orders
- Refunds due
- Rebates due
- Unapplied credit memos
- Unapplied supplier balances
Once a credit enters the ERP, normal controls can process it. A supplier-side balance that was never recorded internally remains outside that process.
7. Partial and split payments hiding the total overpayment
Individual payments can look valid, but their combined value can exceed the amount owed.
For example, a company might pay $20,000 against a $30,000 invoice, then pay another $15,000 through a separate payment run or reference. Neither payment is a full duplicate, but together, they create a $5,000 overpayment.
Partial payments, split payments, and later adjustments can create this pattern when controls don’t compare the cumulative amount paid with the total obligation. The overpayment may only become clear when the transactions are reviewed as a group.
ERP Controls vs. AP Recovery Audits
ERP controls and AP recovery audits operate at different stages of payment control. Transaction controls evaluate invoices as they move through processing, while recovery audits look back at completed activity to find money paid in error.
The main differences are:
| Area |
ERP controls |
AP recovery audits |
| Primary role |
Apply configured checks during transaction processing |
Identify and recover overpayments from historical transactions |
| Timing |
Operate before or during payment processing |
Review transactions after they’ve been processed |
| Information reviewed |
Use transaction and supplier data available during processing |
Review historical transaction data and supporting supplier information |
| Supplier involvement |
Rely mainly on supplier information available within the transaction workflow |
May involve direct supplier contact to validate credits or overpayments |
| Result |
Flag, block, or route a transaction for review |
Confirm a recoverable amount and resolve the claim |
How AP Recovery Audits Identify Recoverable Overpayments
Finding a questionable transaction is only the start of an AP recovery audit. The audit must determine what happened, whether the company is still owed money, and which findings can become valid recovery claims.
The process typically includes four stages:
1. Consolidating historical payment data
At the initial stage, historical payment data from the ERP, payment systems, and other sources in the audit scope is brought into one review.
Supplier identifiers, invoice references, dates, and payment amounts can then be aligned so transactions from different environments are compared consistently.
2. Analyzing transactions for potential recoveries
Historical transactions are screened for potential recoveries, including duplicate payments, partial duplicates, unusual payment patterns, and amounts that don’t reconcile with related records.
Two similar payments may represent a duplicate or separate legitimate obligations, so potential findings must be reviewed before they become recovery claims.
3. Reconciling internal records with supplier information
Transaction analysis alone doesn’t establish every amount owed back to the company. Supplier statements and related account information can be compared with internal payment records to determine if a credit remains open or has already been offset.
Statement reconciliation can establish:
- Whether a credit is still outstanding
- Whether it was applied elsewhere
- Which transaction created the balance
- How much remains recoverable
Incomplete information may require supplier follow-up before the finding can be treated as a recovery claim.
4. Validating and resolving confirmed claims
A potential overpayment becomes a recovery claim only after supporting records confirm that the company is owed money.
Supplier validation can confirm that the supplier received the payment and establish the final amount supported by the claim.
Once confirmed, the recovery can be resolved through a credit, repayment, or another agreed adjustment.
How Recovery Audit Findings Can Strengthen Future Payment Controls
Recovering an overpayment addresses the immediate loss. Recovery findings can also show which payment controls to reconfigure and which workflows to redesign.
Repeated findings can guide specific control changes, including:
| Recovery pattern |
What finance can change |
| Repeated invoice-reference variations |
Refine duplicate-detection criteria |
| Recoveries linked to duplicate supplier records |
Strengthen supplier master validation |
| Cross-system recoveries |
Extend monitoring across ERP environments |
| Recoveries linked to manual exceptions |
Review exception and approval controls |
| Missing credits after returns or cancellations |
Improve information handoffs into AP |
When the same pattern appears across multiple recoveries, finance teams can distinguish a one-off processing error from a recurring control weakness.
Not every finding requires an ERP control change. Instead, some may point to unclear data ownership, weak workflow design, or broken process handoffs.
How apexanalytix Supports AP Recovery and Overpayment Prevention
Preventing overpayments requires strong controls before funds leave the business, while historical losses need a separate recovery path. Large enterprises often need both because new payments continue while older transactions and unresolved claims still require review.
apexanalytix addresses both needs through dedicated overpayment prevention technology and AP recovery audit services.
Both offerings work with existing ERP and payment environments, so finance teams can analyze new payments and review historical activity without replacing current processes.
Relevant solutions include:
- Overpayment Prevention Module: Connects with ERP and payment systems to cross-check invoices in real time, detect subtle duplicate-payment variations, and block confirmed duplicates before payment. Reporting also tracks root causes and exception trends so finance teams can identify recurring issues and strengthen future controls.
- AP Recovery Audit: Reviews historical transactions for duplicate payments, unclaimed credits, and other recoverable amounts. Supplier statement analysis and claim validation establish which findings are recoverable, while post-audit insights show which payment processes contributed to recurring losses.
Thanks to these solutions, apexanalytix boasts $9 billion in overpayments prevented or recovered annually. It also reports a 98% claim uphold rate, with recoveries validated with suppliers before vendor-approved or recommended deductions are presented.
Discover how apexanalytix can help recover past overpayments and prevent new losses before funds leave your business.
FAQ
1. Should AP recovery audits be periodic or continuous?
AP recovery audits can be periodic or continuous. Continuous recovery reviews transactions closer to when they occur, while periodic audits examine a defined historical period.
2. What determines the lookback period for an AP recovery audit?
Available records, supplier terms, claim limits, and internal policies determine the lookback period. The review should cover the historical transactions that still have enough evidence to support a valid recovery claim.
3. Who should own overpayment prevention in a large enterprise?
Finance or AP should handle overpayment prevention. Procurement, supplier management, operations, and other teams should support the process because payment errors can originate outside AP.
4. What key performance indicators (KPIs) should finance teams track to measure overpayment prevention?
Track overpayments prevented, amounts recovered, exception rates, recurring root causes, and repeat overpayment rates. Together, these metrics show how finances are affected and whether repeat losses are declining.
5. How can companies measure the return on investment (ROI) of overpayment prevention and recovery?
Compare the value of prevented and recovered overpayments with the cost of technology, audit resources, and related controls. When calculating the total financial benefit, include both recovered funds and losses stopped before payment.